Investing Fundamentals: Start with a Clear Plan Before Choosing Investments
Investing fundamentals begin with understanding your goal, time horizon, comfort with risk and the role of diversification. A simple household example shows how to turn a broad goal into useful questions—without relying on predictions or promises.
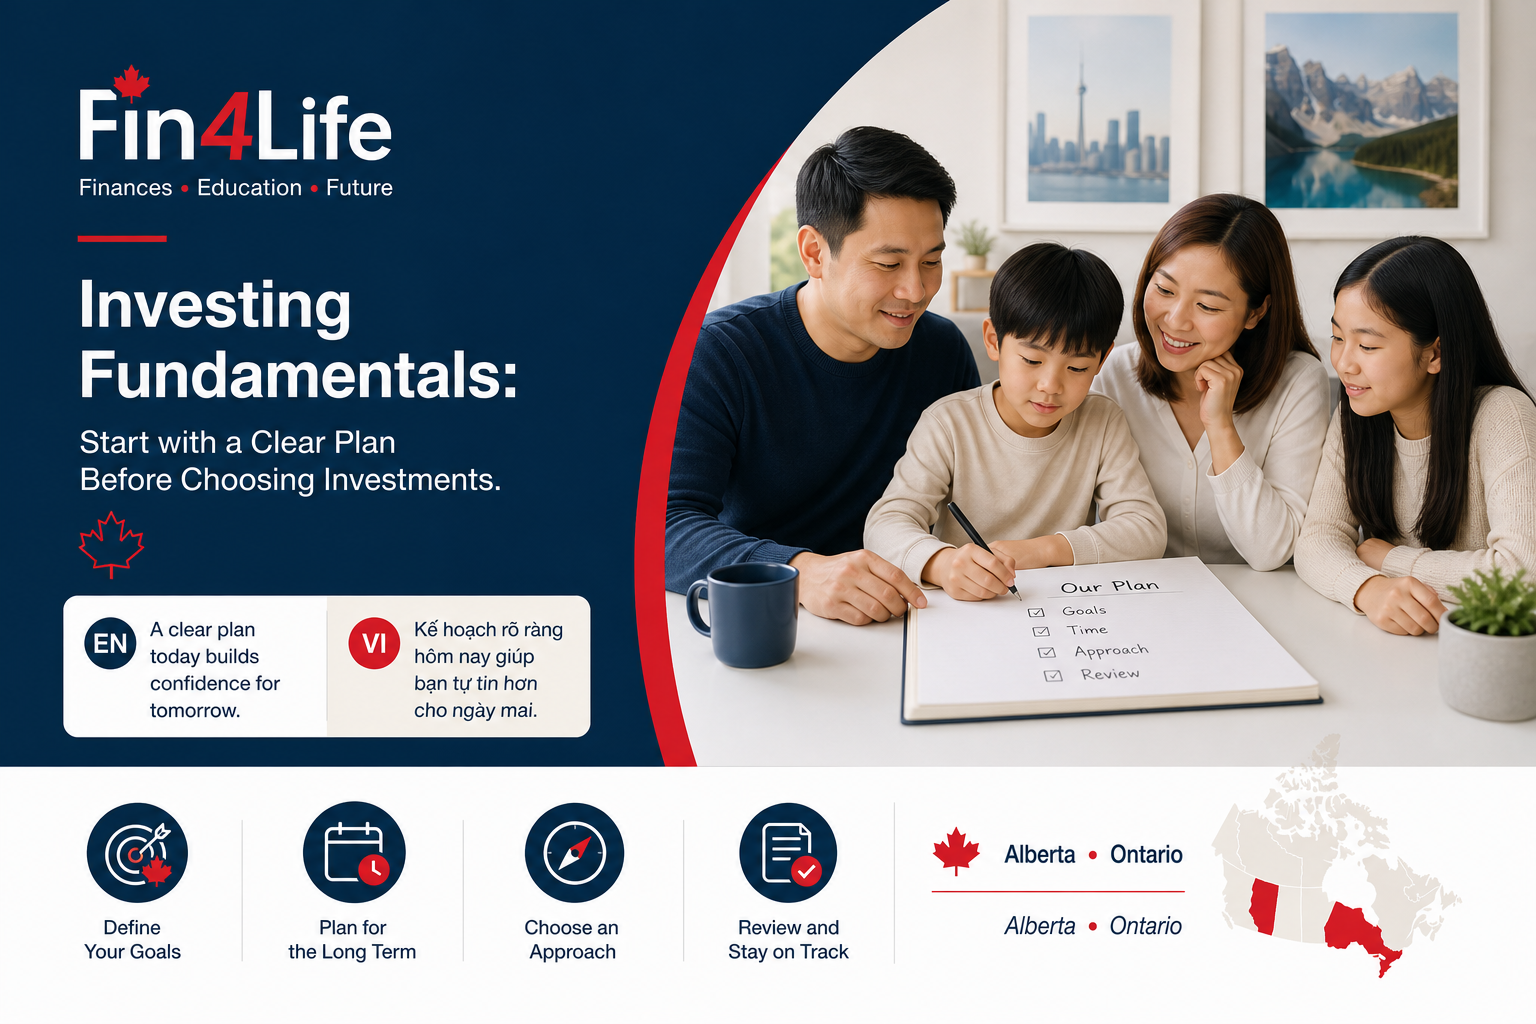
A family in Alberta or Ontario might say, “We want our money to grow,” but that sentence is only a starting point. Before choosing an investment, the family could clarify what the money is for, when it may be needed and how much fluctuation they could reasonably accept.
Consider an everyday example. One household is setting aside money for two different purposes: a possible home-related expense in the nearer term and a longer-term retirement objective. Treating both amounts exactly the same may make the conversation harder. The family can begin by separating the goals, writing down an approximate time horizon for each and identifying what would make them uncomfortable if the value changed.
Four fundamentals can guide the discussion:
1. Goal: What is the money intended to support?
2. Time horizon: When might the money be needed?
3. Risk: How might a temporary decline affect the plan and the household’s ability to stay invested?
4. Diversification: Is the money spread across different investments rather than depending on one holding or one outcome?
These questions do not predict results. They create a structure for learning and comparison. It is also useful to review fees, account features, access to funds and the level of understanding required before making a decision. The right questions can be especially valuable when economic conditions, international competition and trade developments are changing the financial environment.
A practical next step is to make a one-page “investment map”: list each goal, its time horizon, the amount being considered, the potential risks and the questions still unanswered. This is financial education, not personalized investment, tax or legal advice. Circumstances differ, so an individual should consider obtaining appropriate professional guidance before acting.
Families who want to learn more can join an optional workshop on investing fundamentals and bring general questions—without sharing private client information.
General education, not individual financial, tax, legal or insurance advice. Examples are illustrative.